
Teaching Kids About Money: A Beginner Parent’s Guide
“Money doesn’t grow on trees” — every British parent has said it, and every child has wondered why the cash machine disagrees. Teaching kids about money is one of the highest-leverage things a parent can do: the habits formed before age ten shape financial behaviour for life, yet most of us were never taught ourselves — which is exactly why starting feels daunting. The good news: you don’t need to be good with money to teach it, you don’t need much money to demonstrate it, and the methods that work are play, not lectures. This complete beginner’s guide covers what to teach at each age, the practical systems (pocket money, jars, Junior ISAs), and the mistakes to avoid.
Why Starting Early Matters So Much
Research into financial socialisation consistently finds that children’s money habits — saving versus spending impulses, attitudes to debt, comfort with delayed gratification — are substantially formed by age seven to ten, largely by watching parents rather than formal teaching. That’s both the opportunity and the warning: your kids are learning about money from you right now, whether you’re teaching deliberately or not. The parent who visibly compares prices, talks through trade-offs (“we’re choosing the holiday over the new sofa”), and treats saving as normal is teaching constantly.
The stakes are real. Young adults who never learned budgeting basics arrive at university with maintenance loans, overdrafts, and buy-now-pay-later apps — a combination that ruins finances before careers start. A child who learned at eight that money is finite, choices have costs, and saving buys freedom arrives at eighteen with armour. You can’t control the economy they’ll inherit; you can control the operating system they run on.
Ages 3–6: Money Is Real and Finite
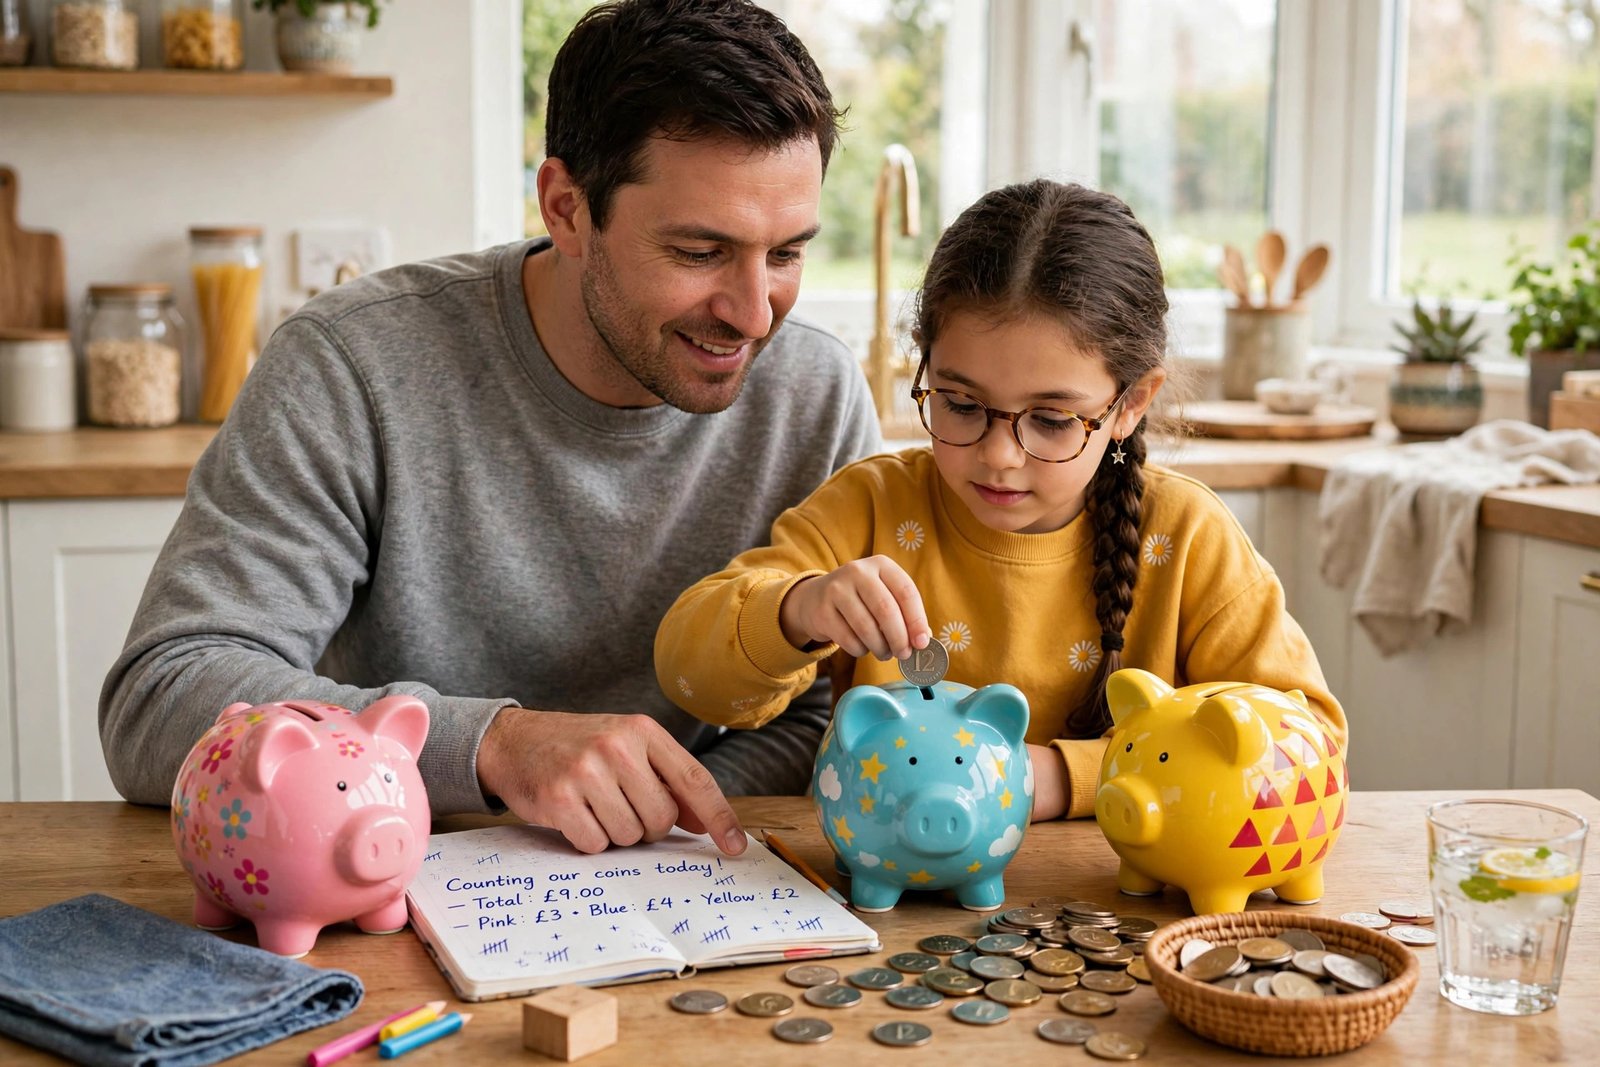
Keep it physical and concrete — abstract numbers mean nothing yet. Let them handle coins, pay for small items with cash (watching money leave teaches what tapping a card never will), and play shop. The core lesson, repeated endlessly: money runs out, and choosing one thing means not choosing another. Three jars work brilliantly at this age — spend, save, share — decorated together and fed with any money received. Don’t lecture; narrate your own choices out loud: “I’m not buying that today because we’re saving for our holiday.” They’re absorbing the logic even when they look bored.
Ages 7–11: Earning, Saving, and the First Goals
Now introduce pocket money with structure: a regular amount (weekly works best — monthly is too abstract), tied lightly to expectations but not strictly to chores (you want them to learn money management, not that family contributions are transactional — though extra paid tasks for bigger goals work well). Help them set a savings goal with a picture on the jar: the £30 Lego set in eight weeks. The waiting is the lesson — delayed gratification practised young becomes financial patience later.
Introduce the bank account around age 7–8 (most UK banks offer children’s savers): the ritual of depositing, watching the balance grow, and understanding interest — even pennies of it — makes saving tangible. This is also the age for the Junior ISA conversation: £9,000 a year can be saved tax-free for their future, and even small family contributions compound enormously over 10+ years. Check current allowances on GOV.UK’s Junior ISA pages. And start the scam-awareness early in age-appropriate form — “never share passwords, even with friends” is the seed of lifelong financial street-smarts.
Ages 12–16: Budgeting, Work, and Digital Money
Teenagers need the real mechanics. Give them a budget to manage: a monthly clothing allowance they control completely is the classic — the first month they blow it on one item and wear old jeans for three weeks teaches more than any lecture. Introduce earning: part-time work, dog walking, tutoring — earned money is valued differently from given money, and the link between effort and income is foundational.
This is also when digital money needs demystifying: show them the bank app, explain what happens when you tap to pay (it’s still real money leaving), and have the debt conversation before lenders have it for them — what interest means, why buy-now-pay-later isn’t free money, what a credit score is. The MoneyHelper guides for talking to children about money are excellent, free, and age-structured. Model the budgeting framework you use yourself — teenagers copy systems, not sermons.
Ages 16+: The Launch Pad
Before they leave home, ensure they can: run a monthly budget, understand payslips and tax, avoid high-interest debt, and grasp investing basics (a Junior ISA converting to an adult ISA at 18 is a perfect teaching moment — their money, their first investment decision, with you advising). Have the honest conversation about student finance: what a maintenance loan really is, how repayments work (9% over the threshold — effectively a graduate tax), and that the “debt” framing misleads. The goal isn’t to make them financial experts — it’s to make them financially literate enough that the system can’t exploit their ignorance.
Pocket Money Done Right (and Wrong)
The details of pocket money matter more than the amount. Right: regular, predictable payments (weekly for under-10s — monthly is too abstract for young brains); the child decides how to split it between jars; you never “advance” next week’s money (that’s a loan-shark lesson in reverse); and natural consequences apply (spent it all on Monday? Tuesday to Sunday is the lesson). Wrong: irregular handouts that teach money appears randomly; docking pocket money as punishment for unrelated behaviour (it teaches money is emotional, not systematic); and topping up when they overspend (which teaches budgets are fictional). The pocket money years are a simulator with tiny stakes — let the simulator do its job. A child who has survived fifty weeks of budgeting £5 arrives at eighteen with instincts no classroom can install.
Mistakes Parents Make (Including the Well-Meaning Ones)
Never talking about money — secrecy teaches that money is shameful or scary. Bailing out every mistake — the £20 overspend at twelve prevents the £2,000 overspend at twenty; let small failures happen. Using money as reward/punishment for behaviour — it tangles emotions with finance. Gendered lessons — research shows girls get less financial teaching than boys in many households; teach everyone everything. Doing it all digitally too early — young children need physical cash to grasp finiteness; screens come later. And preaching without practising — kids detect hypocrisy instantly; the parent lecturing about saving while drowning in card debt teaches the debt, not the lecture.
Teaching kids about money isn’t a subject — it’s a decade-long conversation conducted in supermarkets, at cash machines, and over the kitchen table. Start where they are, keep it concrete, let them make small mistakes, and narrate your own choices. You don’t need to be wealthy or expert. You just need to start talking — because they’re already learning, and you’d rather it was from you.
Frequently Asked Questions
How much pocket money should I give?
There’s no magic number — many UK parents use roughly 50p–£1 per year of age per week, adjusted for what it needs to cover. Regularity and the child’s responsibility for managing it matter far more than the amount.
Should pocket money be tied to chores?
Keep routine family contributions separate from money (everyone helps because they’re family), but paying for extra, optional tasks works well — it teaches the effort-income link without making love transactional.
What’s a Junior ISA and is it worth it?
A tax-free savings account for under-18s (£9,000 annual allowance, check current figures). Money is locked until 18 — excellent for long-term compounding, and a brilliant teaching tool as kids watch it grow.
At what age should kids get a bank card?
Most UK banks offer debit cards from 11 (some pre-paid options from 6–8 with parental controls). The right age is when they understand the money is finite — for many, that’s around 10–12 with a supervised account.